
Clean tech in 2026 is no longer mainly a story about isolated breakthroughs. The market is now testing whether proven technologies can be deployed quickly, affordably and reliably at infrastructure scale. Recent data from the International Energy Agency, the International Renewable Energy Agency and BloombergNEF point in the same direction: solar, batteries, electric vehicles and grid investment are becoming core parts of the energy system, rather than niche experiments.
The main question has shifted. It is less about whether clean technologies work, and more about whether grids, permitting, finance, manufacturing capacity and critical minerals can keep pace. For readers following clean energy markets, clean tech now needs to be assessed as infrastructure, industrial strategy and risk management, as well as environmental innovation.
What clean tech means in the current energy market
Clean tech generally refers to technologies that reduce pollution, cut greenhouse gas emissions, improve energy efficiency or enable cleaner production and consumption. In energy markets, the term usually includes solar PV, wind power, battery storage, electric vehicles, heat pumps, low-emissions fuels, grid software, carbon management, recycling and advanced manufacturing.
The term overlaps with climate tech, but the two are not identical. Climate tech is often used by investors to describe a wider group of solutions aimed at climate mitigation or adaptation, including software, agriculture, carbon removal and resilience tools. Clean tech is usually more closely tied to physical systems: power plants, batteries, factories, vehicles, buildings and industrial equipment.
That distinction matters because the sector’s center of gravity has changed. In the late 2000s and early 2010s, clean tech was often associated with venture-backed hardware companies struggling to scale. In 2026, much of the growth is coming from commercial deployment of technologies that already have supply chains, project finance structures and real demand. The technology frontier still matters, but the clearest market signal is scale.
Key market signals from recent clean tech data
Several current reports show why clean tech is now best understood as a deployment race. The figures below use the latest public information available from major energy institutions and research providers as of August 2026.
| Signal | What recent data shows | Why it matters |
|---|---|---|
| Energy transition investment | BloombergNEF reported that global energy transition investment reached $2.3 trillion in 2025, up 8% from 2024. | Capital is still moving into clean technology deployment despite policy and trade uncertainty. |
| Clean energy investment | The IEA’s World Energy Investment 2026 estimated about $2.2 trillion for grids, storage, renewables, nuclear, low-emissions fuels, efficiency and electrification in 2026, compared with about $1.2 trillion for fossil fuels. | Clean tech investment is now larger than fossil fuel supply investment, although fossil spending remains significant. |
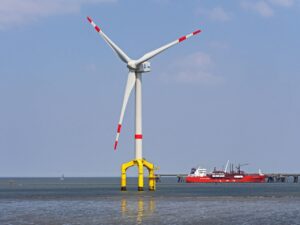
| Renewable capacity | The IEA’s Global Energy Review 2026 estimated annual renewable capacity additions of 800 GW in 2025, with solar contributing roughly three-quarters. | Solar has become the main engine of new clean power capacity, while wind remains important but more exposed to permitting and project delays. |
| Battery storage | The IEA reported 108 GW of new battery storage capacity in 2025, around 40% more than in 2024. | Storage is becoming a core grid technology, not only an add-on for renewable projects. |
| Renewable power costs | IRENA’s 2026 cost analysis reported 2025 global weighted-average LCOE of about $44/MWh for solar PV, $33/MWh for onshore wind and $78/MWh for offshore wind. | Cost competitiveness remains a key driver, although local financing, grid connection and curtailment can change project economics. |
These numbers should not be read as a guarantee that every project is profitable or simple to build. They show something more specific: the mature parts of clean tech are moving at industrial scale, while the main constraints are shifting toward infrastructure, policy and execution.
Why solar, batteries and electric vehicles are setting the pace
Solar and wind are moving from cheap power to system value
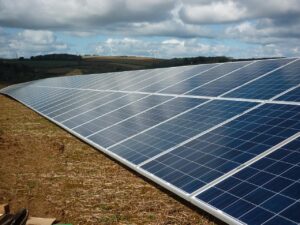
Solar PV remains the clearest example of clean tech scaling through manufacturing. Module production, global competition and standardized project designs have helped make solar one of the lowest-cost sources of new electricity in many markets. IRENA’s latest cost work indicates that more than 90% of utility-scale renewable projects commissioned in 2025 delivered power below the cost of the cheapest new fossil-fuel alternative in their respective markets.
That does not mean solar and wind are automatically sufficient on their own. Levelized cost of electricity is a useful benchmark, but it does not capture every system cost. A power system with higher shares of variable generation also needs transmission, distribution upgrades, demand response, storage, flexible generation, better forecasting and market rules that reward reliability. The next phase of clean tech is therefore not only about building more solar panels and turbines; it is about making clean electricity dispatchable, bankable and grid-friendly.
Batteries are becoming grid infrastructure
Battery storage is one of the most important shifts in the clean tech landscape. The IEA’s Global Energy Review 2026 describes battery storage as the fastest-growing power technology, with 108 GW of additions in 2025 and installed capacity far above the level seen just a few years earlier. Lithium iron phosphate batteries now account for a large majority of deployments, reflecting the market’s preference for chemistries that are lower cost and suitable for frequent cycling.
The role of batteries is also expanding. Early storage projects were often built to support solar output or provide short-duration services. Now batteries are being used for peak shaving, frequency response, congestion management, backup power and renewable integration. Around two-hour systems still dominate many markets, but four-hour systems are becoming more common where evening peaks and solar-heavy grids increase the value of longer discharge.
This makes battery storage a bridge between clean generation and reliable electricity supply. It also creates new pressure points: battery materials, fire safety standards, interconnection queues, revenue model design and recycling capacity all influence how quickly storage can scale.
Electric vehicles bring clean tech into consumer markets
Electric vehicles are the clean tech category most visible to consumers. According to the IEA’s Global EV Outlook 2026, electric car sales grew by about 20% in 2025 and exceeded 20 million units worldwide. The IEA also reported that roughly one in four cars sold globally in 2025 was electric, including battery electric and plug-in hybrid models.
EV growth matters for clean energy because it links transport, power markets and battery supply chains. When charging is managed well, EVs can increase electricity demand in ways that improve asset utilization. When charging is unmanaged, it can add stress to local distribution networks. The value of EVs as clean tech therefore depends not only on vehicle sales, but also on charging infrastructure, grid planning, tariffs, software and the carbon intensity of electricity.
The bottlenecks that now define clean tech competitiveness
Grids are becoming the main constraint
Clean tech deployment increasingly depends on grid capacity. The IEA’s World Energy Investment 2026 estimates that electricity grid spending is approaching $550 billion in 2026, nearly 20% higher year on year. That is a major increase, but many markets still face long interconnection queues, transformer shortages, permitting delays and aging distribution systems.
For developers, grid risk can be as important as technology risk. A solar, wind or battery project with attractive equipment prices can still be delayed or weakened by connection uncertainty. For governments and utilities, grid investment is not just a support function; it is one of the main determinants of how much clean generation can actually be used.
Supply chains remain concentrated
Clean tech has benefited from global manufacturing scale, especially in solar modules and batteries. The same scale has also created concentration risk. The IEA’s Energy Technology Perspectives 2026 highlights that China remains dominant across multiple clean energy technology supply chains, with very high shares in solar PV, batteries and related manufacturing steps.
Concentration is not automatically negative. Large manufacturing clusters can reduce costs, improve quality and accelerate deployment. The risk is that trade disputes, export controls, logistics disruptions or sudden policy changes can affect equipment availability and prices. The IEA’s 2026 analysis also notes that manufacturing investment for key clean energy technologies eased from its 2023 peak, partly because solar and battery manufacturing capacity has grown faster than near-term demand in some segments. See also: EVs.
For clean tech buyers, this means procurement strategy is becoming more sophisticated. Price still matters, but so do supplier diversification, warranty strength, local content rules, shipping exposure, cybersecurity and the availability of spare parts.
Critical minerals are a strategic issue
Batteries, wind turbines, EV motors and grid equipment depend on minerals such as lithium, nickel, copper, graphite, cobalt and rare earth elements. The IEA’s Global Critical Minerals Outlook 2026 warns that supply concentration, export restrictions and underinvestment can create vulnerabilities for clean energy and high-tech industries.
The important point is not that mineral scarcity will stop clean tech. Technology substitution, recycling, new mining projects and chemistry shifts can reduce pressure over time. The point is that mineral supply is now part of energy security. A clean energy strategy that ignores mining, processing, recycling and material efficiency is incomplete.
What this means for clean energy companies and investors
The clean tech market is entering a more disciplined phase. The sector still has strong growth potential, but the simple narratives are less useful than they were a decade ago. More solar, more batteries and more EVs may be directionally correct, but they do not answer the operational questions that determine returns and reliability.
Companies and investors should pay attention to five practical themes:
- Grid readiness: Projects with confirmed interconnection, strong local demand and clear dispatch value are more resilient than projects that rely only on falling equipment prices.
- System integration: Solar-plus-storage, demand response, virtual power plants and flexible loads can create more value than standalone generation in constrained grids.
- Supply chain transparency: Equipment origin, manufacturing capacity, component quality and exposure to trade policy are now central risk factors.
- Financing conditions: Higher interest rates or policy uncertainty can affect capital-intensive clean tech more than headline technology cost curves suggest.
- Market design: Revenue certainty for capacity, flexibility, ancillary services and clean attributes can determine whether clean tech assets are financeable.
This is where clean tech becomes less of a slogan and more of a system planning challenge. The technologies are available, but deployment quality will separate durable markets from overheated ones.
The outlook for clean tech beyond 2026
The outlook is positive but uneven. Mature sectors such as solar PV, battery storage, electric vehicles and grids are likely to remain the largest drivers of near-term investment. Emerging sectors such as low-emissions hydrogen, carbon capture, sustainable aviation fuels and near-zero-emissions industrial materials still need stronger policy support, clearer demand signals and cost reductions before they can scale at the same pace.
The IEA’s Energy Technology Perspectives 2026 estimates that the combined global market value for selected clean energy technologies reached nearly $1.2 trillion in 2025 and could grow substantially by 2035 depending on policy direction. That projection should be read as a scenario-based outlook, not a certainty. Policy, trade rules, commodity prices, permitting and public acceptance will all affect the speed and shape of growth.
The most likely near-term pattern is not a smooth transition, but a competitive buildout. Countries will try to secure domestic industries, utilities will race to expand grids, manufacturers will compete on cost and resilience, and energy users will look for cleaner power that is also reliable and affordable. Clean tech’s next test is execution at scale.
Frequently asked questions
What is clean tech?
Clean tech refers to technologies that reduce emissions, pollution, waste or resource intensity. In energy, it commonly includes renewable power, batteries, EVs, heat pumps, efficient equipment, grid technologies, low-emissions fuels and carbon management.
Is clean tech the same as clean energy?
No. Clean energy usually refers to low-emissions energy sources and systems, such as renewables, nuclear, storage and efficiency. Clean tech is broader because it can include manufacturing, transport, industrial processes, recycling, software and materials that support cleaner economic activity.
Which clean tech sectors are most mature?
Solar PV, onshore wind, lithium-ion batteries, electric cars and some energy efficiency technologies are among the most mature. Offshore wind, hydrogen, carbon capture and low-emissions industrial materials are developing, but their economics depend more heavily on policy support, infrastructure and project execution.
Why are grids so important for clean tech?
Grids determine how much clean electricity can be connected, delivered and used. Without transmission upgrades, distribution investment, storage, digital controls and flexible demand, low-cost renewable generation can face delays, congestion or curtailment.
What is the biggest risk for clean tech in 2026?
The biggest risk is not one single technology failure. It is the combination of grid bottlenecks, policy uncertainty, financing costs and concentrated supply chains. These factors can slow deployment even when the underlying technologies are cost-competitive.