
RWE wind at a glance in 2026
RWE wind activity in 2026 is best read through two different operating conditions. In Europe, the company is advancing large offshore projects in the UK, Germany, Denmark and the Netherlands, while still adding onshore capacity in selected markets. In the United States, RWE remains active in renewables and power generation, but its offshore wind plans have been reshaped by federal policy uncertainty and a settlement with the U.S. Department of the Interior. For readers following wind energy, the key issue is no longer only installed megawatts. RWE’s wind portfolio is increasingly defined by construction timing, auction-backed revenue, supply chain delivery, grid connection and political risk.
According to RWE’s Annual Report 2025 and online reporting, wind remained the company’s largest renewable technology at the end of 2025, with about 13.0 GW of pro-rata wind capacity across offshore and onshore assets. Offshore wind accounted for about 3.3 GW pro rata, while onshore wind stood at about 9.7 GW pro rata. Those figures provide the baseline for assessing the projects that moved forward during 2026.
Why offshore wind is the center of the RWE wind story
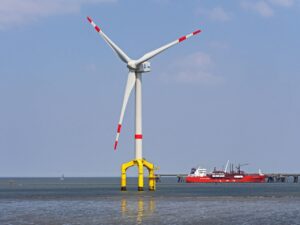
Offshore wind attracts most of the attention because single projects are large, capital intensive and closely tied to government auction systems. RWE’s current offshore growth is concentrated in the North Sea region, where several major projects are moving through construction and commissioning.
RWE said in an August 31, 2026 Nordseecluster update that Sofia in the UK, Thor in Denmark, OranjeWind in the Netherlands and Nordseecluster in Germany together represent about 4.8 GW of total generation capacity, with RWE’s share at about 3.1 GW. The same update stated that RWE intends to expand its offshore wind capacity by a net 5 GW by 2031. That target should be treated as a company plan rather than a guaranteed outcome, because offshore schedules depend on installation vessels, grid assets, consenting, weather windows and financing discipline.
| Project | Market | Capacity | 2026 status | Strategic role |
|---|---|---|---|---|
| Sofia Offshore Wind Farm | United Kingdom | Up to 1.4 GW | RWE announced on June 11, 2026 that all 100 turbines had been installed, with electrical testing and commissioning continuing. | Adds a very large UK offshore asset and demonstrates delivery of high-capacity turbines far from shore. |
| Thor Offshore Wind Farm | Denmark | About 1.1 GW | Project communications say the first turbines were installed in 2026 and full operation is expected in 2027. | Strengthens RWE’s position in Denmark and includes lower-carbon material and recyclable blade elements. |
| Nordseecluster | Germany | About 1.6 GW | RWE said on August 31, 2026 that 22 turbines had been installed for Nordseecluster A, with commissioning of the 660 MW phase expected at the beginning of 2027 and Nordseecluster B adding 900 MW from 2029. | Supports German industrial decarbonisation and long-term power supply contracts. |
| OranjeWind | Netherlands | 795 MW | RWE announced on September 1, 2026 that the first monopile had been installed, with 53 turbines planned and full commissioning expected in 2028. | Links offshore wind with Dutch system integration, hydrogen and flexible demand concepts through the RWE and TotalEnergies joint venture. |
The offshore portfolio shows a clear pattern. RWE is not relying on one flagship asset alone. It is spreading construction across several North Sea markets, often with partners such as Norges Bank Investment Management or TotalEnergies. That reduces exposure to any single project, but it also raises the coordination burden across foundations, turbines, export systems, ports and grid operators.
Project execution is now as important as project size
Offshore wind headlines often focus on capacity. The more practical question is whether projects can move from award to construction to first power without major delays. RWE’s 2026 milestones point to progress, but they also show how long offshore wind buildout can take.
Sofia is a useful example. RWE reported that final turbine installation was completed on June 10, 2026, after installation work that began in March 2025. The project uses 100 Siemens Gamesa 14 MW-class turbines and is located more than 200 kilometers off the UK coast. Even after turbine installation, the project still needed testing and commissioning of its high-voltage direct current system before the turbines could be fully connected. For investors and energy buyers, that distinction matters: installed turbines are not the same as fully operational generation.
Nordseecluster follows a phased approach. Nordseecluster A is scheduled to bring 660 MW into service at the beginning of 2027, while Nordseecluster B is expected to add 900 MW from 2029. RWE has said the combined project is expected to generate around 6.5 TWh of electricity per year once complete. The phased schedule reduces some execution pressure, but it also means the full value of the asset arrives over several years rather than in one step.
OranjeWind adds another dimension because it is being presented not only as a wind farm, but also as a system integration project. The September 2026 monopile milestone marked the start of offshore construction. RWE said inter-array cable installation is planned for late 2026, turbine installation is expected through 2027, and full commissioning is expected in 2028. The project’s value will therefore depend on generation output and on how well the surrounding Dutch energy system can absorb variable offshore power.
Onshore wind remains important but less headline-driven
Offshore wind may dominate public discussion, but RWE’s onshore fleet is larger by installed wind capacity. RWE reported about 9.7 GW of pro-rata onshore wind capacity at the end of 2025. The onshore business is also more geographically spread, with the United States as a major market and Europe as a second growth region focused on countries including Germany, the UK, Italy, Poland and France.
In 2026, RWE continued to complete smaller onshore projects that are relevant to regional power supply, even if they do not match offshore projects in scale. In the UK, the company announced in August 2026 that construction was complete at the 70 MW Enoch Hill onshore wind farm in East Ayrshire, Scotland. The same update said Enoch Hill and Camster II together added 106 MW of new Scottish onshore generation capacity in 2026. Compared with a 1.4 GW offshore project, 106 MW may look modest. But onshore projects can often reach local grids faster, support regional supply chains and diversify a developer’s construction risk.
The onshore story is also tied to repowering and permitting. Mature European wind markets contain many older turbines on sites with good wind resources. Replacing older machines with fewer, larger and more efficient turbines can increase output without opening entirely new development zones. Repowering still depends on planning rules, grid capacity, community acceptance and environmental studies.
What RWE’s 2026 results say about wind momentum
Financial performance does not fully measure wind strategy, but it helps show whether operating conditions and capacity additions are translating into earnings. In its August 13, 2026 first-half results, RWE reported adjusted EBITDA of €810 million in Offshore Wind for the first half of 2026, compared with €643 million in the same period of 2025. The company attributed the improvement primarily to higher generation volumes after wind conditions normalised following weak winds in the first half of 2025.
RWE’s Onshore Wind/Solar segment also improved, with adjusted EBITDA of €1.016 billion in the first six months of 2026, compared with €830 million in the first half of 2025. RWE said the increase was driven mainly by continued capacity expansion and more favourable wind conditions in Europe, partly offset by currency effects from converting U.S. dollars into euros.
These figures underline a recurring feature of wind power. Once assets are built, production and earnings still vary with weather patterns. A strong half-year does not remove resource risk, and a weak wind period does not necessarily undermine the long-term asset base. For energy market readers, the more useful takeaway is that RWE’s wind earnings are influenced by both structural growth and short-term wind conditions. See also: clean energy.
UK contracts improve visibility but do not remove delivery risk
The UK remains one of the most important markets in the RWE wind pipeline. On January 14, 2026, the UK Department for Energy Security and Net Zero published Allocation Round 7 results for Contracts for Difference. The official results listed offshore wind awards including RWE-related Dogger Bank South East, Dogger Bank South West, Norfolk Vanguard East, Norfolk Vanguard West and Awel y Môr projects. RWE has described the five UK projects as collectively expected to deliver up to 6.9 GW of capacity, with an RWE share of about 3.5 GW.
Contracts for Difference can improve revenue visibility because they set a framework around power prices. That helps developers, lenders and supply chain partners plan around future cash flows. But CfDs do not build wind farms by themselves. Developers still need to manage inflation, vessels, grid connections, seabed conditions, environmental requirements and final investment discipline. In that sense, the UK awards strengthen RWE’s pipeline, while also creating a large execution queue stretching into the late 2020s and early 2030s.
U.S. offshore policy has become a clear risk factor
The sharpest policy signal in 2026 came from the United States. On August 6, 2026, RWE U.S. Offshore announced a settlement with the U.S. Department of the Interior for US$1.22 billion. The agreement included relinquishment of RWE offshore wind leases in the New York Bight, off California and off Louisiana. BOEM also stated that the Department of the Interior had cancelled and rescinded the Lake Charles lease in the Gulf of America on August 4, 2026.
This does not mean RWE has exited the U.S. energy market. RWE Americas said it plans to invest about €17 billion in the United States over six years and grow generation capacity from about 13 GW across 27 states to 22 GW by 2031. However, the offshore settlement shows that U.S. federal policy can materially change the risk profile of marine wind development. For RWE, the practical result is a stronger emphasis on offshore growth markets with clearer near-term permitting and auction frameworks, particularly in north-west Europe.
What to watch next
For 2026 and beyond, the RWE wind story should be tracked through practical indicators rather than one headline capacity number.
- Whether Sofia completes electrical commissioning and begins contributing at scale to UK renewable generation.
- Whether Thor reaches full operation in 2027 as scheduled and how its lower-carbon material choices influence future procurement.
- Whether Nordseecluster A enters service at the beginning of 2027 and whether Nordseecluster B remains on track for the 2029 phase.
- Whether OranjeWind progresses from monopiles to cables and turbines without major delay before expected 2028 commissioning.
- Whether UK CfD-backed projects move through final investment decisions, procurement and grid milestones on schedule.
- Whether U.S. policy conditions improve enough for offshore developers to rebuild confidence, or whether capital continues shifting to onshore renewables, storage, flexible generation and European offshore projects.
RWE’s wind strategy is not simply an expansion narrative. It is a test of how a large energy company balances growth, risk sharing, capital discipline and power market volatility. The company has a sizeable operating base, a visible European offshore construction pipeline and meaningful onshore activity. Its biggest challenge is converting that pipeline into reliable generation while navigating policy uncertainty and supply chain constraints.
Frequently asked questions
How much wind capacity does RWE have?
RWE reported about 13.0 GW of pro-rata wind capacity at the end of 2025, including about 3.3 GW of offshore wind and about 9.7 GW of onshore wind. The exact number can differ depending on whether capacity is reported on a pro-rata basis or under IFRS consolidation rules.
What are RWE’s main offshore wind projects in 2026?
The most visible projects are Sofia in the UK, Thor in Denmark, Nordseecluster in Germany and OranjeWind in the Netherlands. These projects are at different stages, from turbine installation and commissioning to foundation installation and phased construction.
Is RWE still active in U.S. wind?
RWE remains active in the U.S. energy market and has a major onshore renewables presence. However, in August 2026 the company agreed to relinquish several U.S. offshore wind leases as part of a settlement with the U.S. Department of the Interior, reflecting a more difficult policy environment for U.S. offshore wind.
Why do RWE wind results vary from year to year?
Wind earnings depend on installed capacity, power prices, contract structures, operating availability and wind resource. RWE’s first-half 2026 offshore results improved partly because wind conditions normalised after weak winds in the first half of 2025.
What is the key risk for RWE wind growth?
The main risks are project execution, permitting, grid connection, supply chain availability, interest rates and policy stability. Offshore wind projects are especially sensitive because they require large upfront investment and long construction timelines.