
Why solar energy companies matter now
Solar energy companies have moved from a growth niche into mainstream power-market planning. Climate policy is part of the story, but it is not the only driver. Solar also benefits from modular construction, shorter development cycles than many conventional power projects, long-term technology cost declines, and rising electricity demand from buildings, industry, data centers and electrification. According to the International Renewable Energy Agency’s 2026 capacity statistics, solar power added about 510 GW globally in 2025, making it the dominant source of new renewable capacity. The International Energy Agency also reported that solar PV generation rose by about 600 TWh in 2025, the largest one-year increase recorded for any electricity source outside post-crisis recovery years.
Those figures do not make every solar company low risk, or equally competitive. They show that the sector is now large enough for buyers, investors and energy users to separate manufacturers, developers, installers, asset owners and service providers more carefully. A useful evaluation starts with the company’s role in the value chain, not with a broad label such as “solar provider.”
The main types of solar energy companies
The solar industry is a chain of specialized businesses. Some companies operate across several stages, but many are strong in one area and exposed in another. That distinction explains why two businesses can both be called solar companies while facing very different risks, margins and capital needs.
Manufacturers
Manufacturers produce polysilicon, wafers, cells, modules, inverters, racking, trackers, cables and other system components. Their performance depends on factory utilization, input costs, technology efficiency, product quality, trade policy and access to buyers. Module assembly capacity can expand faster than upstream wafer or cell capacity, so headline manufacturing numbers need careful reading. A company may report strong nameplate capacity while still facing limited output, weak margins or exposure to imported components.
Developers and EPC contractors
Developers originate projects, secure land or rooftops, manage grid studies, obtain permits, negotiate power-purchase agreements and arrange financing. EPC contractors handle engineering, procurement and construction. In utility-scale solar, stronger developers are often those that manage interconnection queues, permitting timelines and offtake agreements with discipline. For EPC firms, project execution is central to value: procurement timing, construction quality, safety performance and schedule control can all affect final economics.
Residential and commercial installers
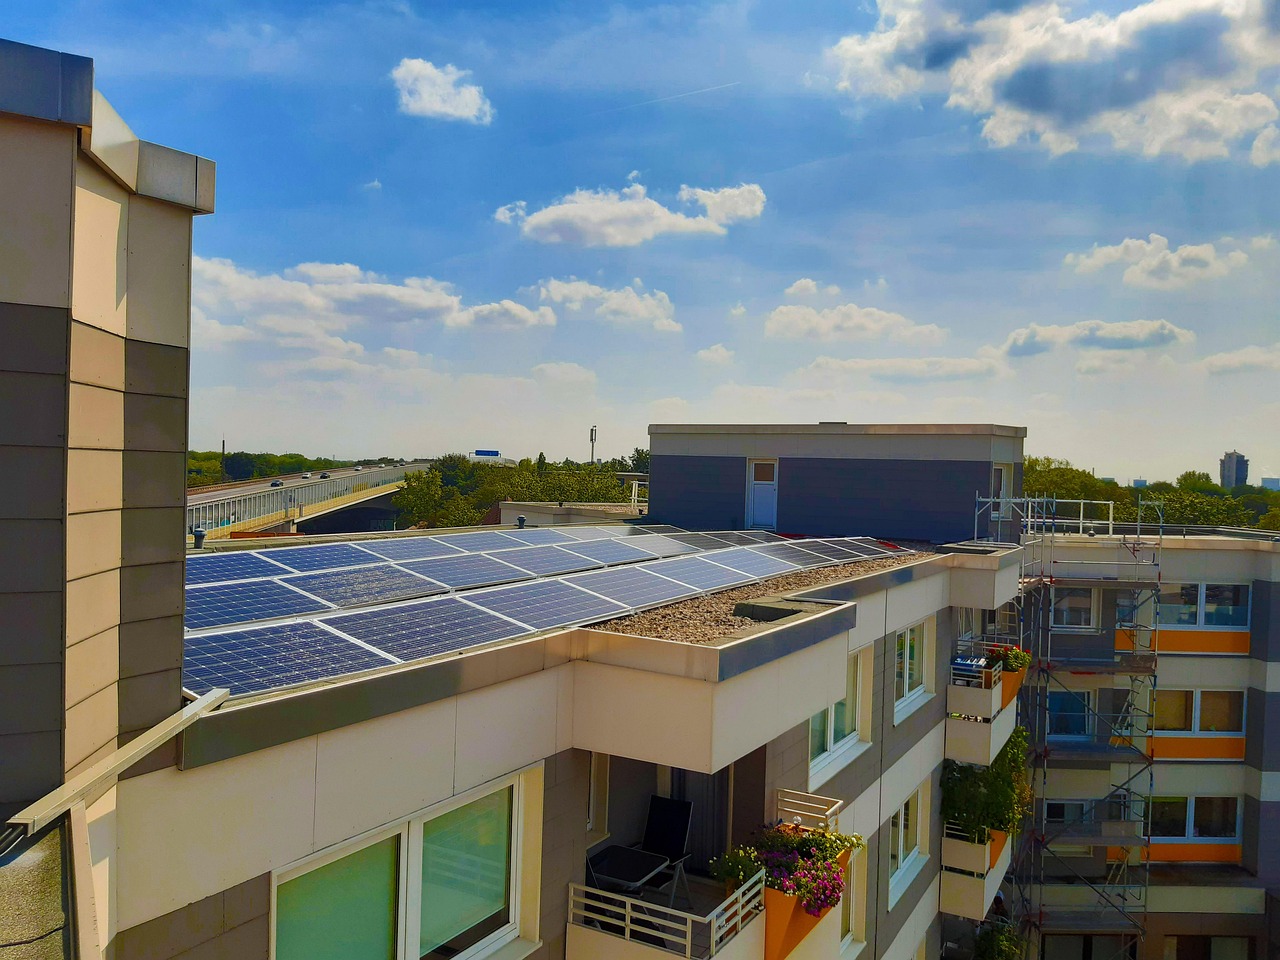
Installers sell and build rooftop or small ground-mounted systems for homeowners, schools, farms, warehouses and commercial buildings. Their quality is measured less by global scale and more by design accuracy, local permitting knowledge, roof assessment, electrical workmanship, customer service and long-term support. Financing transparency is also important because residential customers may need to compare cash purchase, loan, lease and power-purchase agreement options on different terms.
Asset owners, operators and software providers
Some companies own solar assets and earn revenue by selling electricity. Others provide operations and maintenance, monitoring software, forecasting, grid services, virtual power plant platforms or battery integration. As solar penetration increases, these companies become more important because performance management, curtailment response and storage dispatch can influence lifetime value.
What separates stronger solar companies from weaker ones
Solar is modular, but it is not simple. A reliable company should be assessed on evidence of execution rather than marketing language. The following framework is more useful than a broad ranking list because the right comparison depends on project type, market location and contract structure.
| Evaluation area | What to check | Why it matters |
|---|---|---|
| Business model | Manufacturer, installer, developer, EPC, asset owner or service provider | Each model has different risks, margins and capital needs |
| Project record | Completed projects, operating assets, local permits and relevant system sizes | Past delivery is a better signal than broad claims |
| Supply chain | Module source, inverter choice, warranty backing and exposure to trade restrictions | Equipment delays or weak warranties can affect cost and reliability |
| Financial strength | Balance-sheet quality, financing partners, debt exposure and cash flow | Solar projects require long timelines and after-sales support |
| Technical quality | Design assumptions, degradation rates, shade analysis and monitoring plan | Small modeling errors can reduce long-term production |
| Operations support | Maintenance plan, response time, spare parts and performance reporting | Solar value is earned over decades, not only at installation |
For more context on solar market developments, visit Econergy solar insights.
Market signals shaping company strategy
Several market signals are changing how solar companies compete. First, solar is now one of the main sources of new power capacity, especially in the United States. The U.S. Energy Information Administration reported in February 2026 that developers planned to add 86 GW of utility-scale electric generating capacity in 2026, with solar representing 51% of planned additions, battery storage 28% and wind 14%. This reinforces the view that solar companies are increasingly evaluated alongside storage and grid-integration providers, not only as panel suppliers.
Second, the U.S. market is large but uneven. SEIA and Wood Mackenzie reported that the U.S. solar industry installed 43.2 GWdc in 2025, down 14% from 2024, while solar still accounted for 54% of new U.S. electricity-generating capacity. The same report noted that U.S. module manufacturing capacity grew to 65.5 GW in 2025, up from 42.5 GW at the end of 2024, but actual production remained below domestic demand. This gap matters because buyers may hear about manufacturing expansion while still facing procurement constraints or component-specific shortages.
Third, solar and storage are becoming more closely linked. Higher solar penetration can create midday oversupply in some regions and evening capacity needs in others. Batteries can shift output, reduce curtailment, provide backup power and help projects respond to time-of-use tariffs or grid-service opportunities. Companies that understand both PV and storage may be better positioned than firms that treat batteries as an add-on product.
Risks buyers and investors should not ignore
The strongest solar demand story still includes real constraints. Policy risk is one of them. Tax-credit schedules, domestic-content rules, tariff investigations and permitting requirements can change project timing and economics. SEIA and Wood Mackenzie’s 2025 review highlighted how revised tax-credit timelines, safe-harbor strategies and trade actions affected project scheduling in the U.S. market. This is especially relevant for utility-scale developers and manufacturers with long investment cycles.
Interconnection is another major constraint. A project is not bankable simply because it has land, panels and a buyer. It needs a viable path to connect to the grid, and the cost of network upgrades can change project economics. For commercial and residential systems, local permitting, utility approval and net billing rules can also affect returns. See also: clean energy.
Supply-chain quality matters as much as supply-chain location. A domestic or local label does not automatically guarantee reliable output, warranty strength or price stability. Buyers should ask whether a company can document the origin of major components, explain warranty coverage and support replacement parts over time.
Financing risk is also important. Solar has high upfront costs and long payback periods, so interest rates, tax-equity availability, customer credit quality and contract structure can affect project viability. For homeowners and small businesses, the lowest monthly payment is not always the best economic option if escalators, fees or maintenance responsibilities are unclear.
How to compare companies by project type
Residential customers should focus on local experience, roof and electrical assessment, production modeling, workmanship warranty, equipment warranty and financing clarity. A strong installer should explain expected annual output, seasonal variation, battery limitations, utility approval steps and what happens if production falls below the model.
Commercial and industrial buyers should compare companies on tariff analysis, demand-charge reduction, roof condition, structural review, insurance requirements, operations access and contract flexibility. For a warehouse, school or factory, the best proposal is not necessarily the largest system. It is the system that matches load profile, roof life, utility rules and capital planning.
Utility-scale buyers and investors should examine the developer’s interconnection position, permitting status, land control, offtake agreement, equipment procurement plan and financing assumptions. A large pipeline can look attractive, but projects at different stages have very different probabilities of completion.
For manufacturing partnerships, the key questions are factory utilization, technology roadmap, customer concentration, upstream material access and warranty bankability. Capacity announcements are useful, but actual shipments, margins and quality records are more revealing.
Frequently asked questions
What do solar energy companies do?
They design, manufacture, finance, install, own, operate or service solar power systems. Some focus on one part of the value chain, while others combine development, construction, storage and long-term asset management.
Are larger solar companies always better?
No. Larger companies may have stronger purchasing power and financing access, but local installers or specialized developers can outperform them in permitting, customer service or niche project types. The better question is whether the company has proven experience with the specific system size, location and contract structure you need.
Why are batteries often discussed with solar projects?
Batteries help shift solar output from sunny hours to higher-value periods, improve resilience, reduce curtailment and support grid services. They are not required for every project, but they are becoming more important as solar becomes a larger share of electricity supply.
What is the biggest mistake when comparing solar companies?
The most common mistake is comparing only headline price or installed capacity. A serious evaluation should include design assumptions, equipment quality, grid approval risk, financing terms, warranty backing and operations support.
What this means for the sector
The solar market is expanding, but it is also becoming more demanding. Growth now depends on grid access, storage integration, stable supply chains, financeable contracts and long-term performance. Solar energy companies that can manage these details are better positioned than firms relying only on strong demand or low module prices. For buyers and investors, the practical lesson is clear: evaluate the company’s role, evidence and risks before comparing price. In a maturing market, execution quality is becoming just as important as technology adoption.