
Key takeaways for onshore wind power in 2026
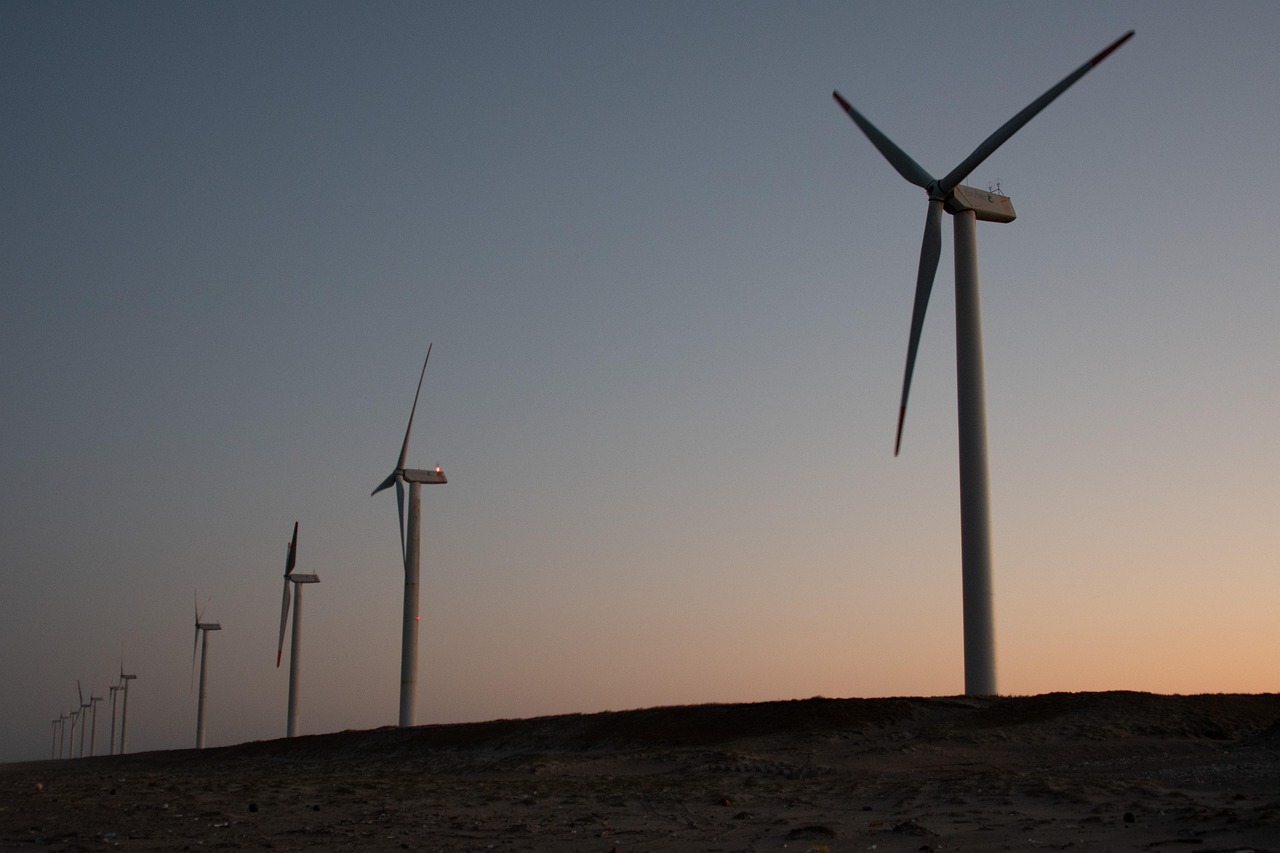
Onshore wind power remains the backbone of the global wind sector. In 2026, the central question is no longer whether the technology can perform at scale. It can. The pressure now sits around grid access, permitting, supply-chain execution and local planning, all of which must keep pace with record installation volumes.
According to the Global Wind Energy Council’s Global Wind Report 2026, wind power added 165 GW of new capacity in 2025, including 155.3 GW from onshore projects. Onshore wind therefore supplied the overwhelming majority of new wind capacity added worldwide. For readers tracking the wider wind energy market, the message is direct: onshore wind is mature, cost-competitive and scalable, but its value now depends increasingly on system integration rather than turbines alone.
Why onshore wind still leads global wind deployment
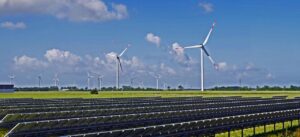
Onshore wind has a structural advantage over offshore wind in most markets. Projects are generally faster to build, easier to finance, less complex to maintain and less exposed to marine engineering risk. Offshore wind remains important for countries with dense coastal demand and limited land availability, but onshore projects continue to account for most annual wind installations.
GWEC’s 2026 reporting shows how dominant the onshore segment remains. Of the 165 GW of global wind capacity connected in 2025, 155.3 GW was onshore and 9.3 GW was offshore. Total global wind capacity reached about 1,299 GW in 2025. The largest additions came from China, the United States, India, Germany and Brazil, which together represented most of the year’s new wind installations.
The International Energy Agency’s Global Energy Review 2026 points in the same direction from a broader power-sector perspective. It estimates that annual wind capacity additions rose by nearly 40% globally in 2025, reaching a new record of around 160 GW. Solar PV grew faster in absolute terms, but wind remained the second-largest contributor to new renewable capacity. It also remains an important complement to solar because wind generation often follows different daily and seasonal patterns.
What changed in the latest market data
The 2025 installation year is important because it shows both acceleration and market concentration. China was the main driver, with GWEC reporting 120.5 GW of new wind capacity in 2025 and more than 110 GW of new onshore wind. The IEA separately reported that China commissioned nearly 117 GW of wind capacity in 2025. India also had a strong year: according to the IEA, wind additions more than doubled to over 6 GW, while GWEC reported 6.3 GW of total wind additions.
The European Union added about 13 GW of onshore wind in 2025, according to the IEA, while offshore additions fell to about 1 GW. That split matters. Even in a region with long-running offshore ambitions, onshore wind remained the larger near-term source of new wind capacity. The United States also rebounded in onshore deployment in 2025, although policy and interconnection uncertainty continued to affect the development pipeline.
| Indicator | Latest reported figure | What it means |
|---|---|---|
| Global wind additions in 2025 | 165 GW reported by GWEC | Wind set a new annual installation record. |
| Onshore wind additions in 2025 | 155.3 GW reported by GWEC | Onshore projects supplied most new wind capacity. |
| Global cumulative wind capacity | About 1,299 GW in 2025 reported by GWEC | Wind is now a terawatt-scale power source. |
| China’s 2025 wind additions | About 117 GW to 120.5 GW across IEA and GWEC reporting | China dominated annual market growth. |
| EU onshore wind additions | About 13 GW in 2025 reported by the IEA | Onshore wind remained central to Europe’s wind buildout. |
Cost competitiveness is strong, but project economics are more local
Onshore wind is often described as a low-cost renewable technology, and recent cost data supports that view. IRENA’s Renewable Power Generation Costs in 2025 report placed the global weighted-average levelised cost of electricity for onshore wind at USD 33 per MWh in 2025. That figure should not be treated as a universal project price. It is a global weighted average, and actual economics vary by wind resource, turbine choice, financing cost, grid connection distance, land agreements, local content rules and curtailment risk.
The technology trend still favours higher energy capture. Modern land-based turbines use taller towers, larger rotors and more site-specific designs than earlier generations. U.S. Department of Energy material based on land-based wind market reporting shows that average hub heights and rotor diameters have risen substantially over the past two decades. NREL’s 2024 Annual Technology Baseline also models near-future land-based turbine configurations with ratings from 3.3 MW to 8.3 MW, rotor diameters from 148 meters to 196 meters and hub heights from 100 meters to 140 meters.
These larger machines can improve output at lower-wind sites, but they also change the development equation. Larger components require stronger logistics planning, suitable roads, crane availability, community consultation and careful siting around aviation, radar, wildlife and visual-impact constraints. Turbine scaling lowers energy cost only when the surrounding project system can absorb the added complexity.
The bottleneck has shifted from turbines to grids
For many markets, the hardest question is no longer whether developers can source turbines. It is whether a project can secure a timely, firm and economically viable grid connection. The IEA’s Electricity 2026 analysis describes grids as a major bottleneck for connecting new generation, storage and demand. It estimates that more than 2,500 GW of renewable, large-load and storage projects were stalled in grid queues worldwide in 2025.
This issue directly affects onshore wind. Good wind resources are often located far from large demand centers. If transmission expansion is delayed, projects may wait years in interconnection queues or operate with curtailment after commissioning. The IEA notes that new grid infrastructure can take 5 to 15 years to plan, permit and complete, while renewables projects such as wind and solar can often be built in 1 to 5 years. That mismatch can turn a technically strong wind site into a financially uncertain project.
Grid-enhancing technologies may help. The IEA has highlighted dynamic line rating, advanced power-flow control, non-firm connection agreements, reconductoring and better queue management as ways to unlock capacity faster than building entirely new transmission lines. These measures do not remove the need for new grids, but they can reduce wasted time and help viable wind projects connect sooner. See also: clean energy.
How onshore wind compares with solar and offshore wind
Onshore wind does not compete with solar PV in a simple winner-takes-all way. Solar is now adding more capacity globally, but wind often produces at different hours and in different seasons. That makes a mixed renewable portfolio more valuable than either technology alone. In many power systems, wind output can support evening, nighttime or winter demand more effectively than solar PV, depending on local weather patterns.
Offshore wind, by contrast, can offer higher capacity factors and proximity to coastal demand centers, but projects are usually larger, more capital intensive and exposed to marine construction risk. Recent offshore auction challenges in several markets show that high interest rates, supply-chain pressure and contract design can quickly affect project viability. Onshore wind is not immune to inflation or permitting problems, but it generally has a shorter development cycle and a broader geographic base.
| Technology | Main advantage | Main constraint |
|---|---|---|
| Onshore wind | Mature, scalable and relatively low-cost | Land use, permitting, local acceptance and grid access |
| Offshore wind | Large projects and strong wind resources near coastal demand | Higher capital cost, marine construction risk and auction uncertainty |
| Solar PV | Fast deployment and modular construction | Daytime output profile and growing need for storage or flexibility |
Planning priorities for the next phase of onshore wind
The next phase of onshore wind power will favour markets that treat generation, grid and demand as one system. The IEA’s 2024 report on integrating solar and wind warned that without timely integration measures, power systems could jeopardise up to 15% of variable renewable generation in 2030. That warning is especially relevant for wind-rich regions where grid expansion and flexibility investment lag behind project development.
Practical priorities are becoming clearer. First, grid connection processes need stronger screening so speculative projects do not block ready-to-build capacity. Second, governments and system operators need to plan transmission around high-quality renewable zones rather than approving projects one by one without network visibility. Third, wind development should increasingly be paired with storage, flexible demand, hybrid solar-wind projects or market rules that reward generation when the system needs it most.
Local engagement also remains critical. Onshore wind can bring lease payments, local taxes and rural economic activity, but it can also face opposition over landscape change, sound, shadow flicker, wildlife and property concerns. Early consultation does not guarantee approval, but it can reduce the risk of late-stage conflict and improve project design. For an industry operating at terawatt scale, public acceptance is not a soft issue; it is a deployment constraint.
Frequently asked questions
What is onshore wind power?
Onshore wind power is electricity generated by wind turbines installed on land. Utility-scale projects typically use multiple turbines connected to a local substation and then to the wider transmission or distribution network.
Is onshore wind cheaper than offshore wind?
In most markets, onshore wind has lower capital cost and lower levelised electricity cost than offshore wind. However, final project economics depend on wind resource quality, financing, grid connection, curtailment, permitting conditions and local construction costs.
Why are grid connections so important for onshore wind?
A wind farm only creates full value when it can deliver electricity to the grid at the right time and price. Weak transmission, long interconnection queues or frequent curtailment can reduce revenue even when the wind resource is strong.
Will onshore wind keep growing after 2026?
Most industry and energy-agency outlooks expect continued growth, but the pace will depend on permitting, grid investment, auction design, supply-chain capacity and public acceptance. The technology is mature; the main uncertainty is how quickly markets can remove non-turbine bottlenecks.